What Values-Based Financial Goals Really Mean
Values based financial goals are money targets built around what genuinely matters to you — time with family, creative freedom, health, security — rather than generic milestones like a specific salary or net worth number borrowed from someone else's life. Instead of asking 'how much should I be saving,' you start by asking what a good life actually looks like for you, then work backward into the numbers.
As a nutrition coach, I see the same pattern in money that I see in food: clients who chase a generic goal (lose 20 pounds, save $50,000) burn out fast, while clients who anchor to a real value (have energy to play with my kids, never worry about a medical bill) stick with unglamorous daily habits far longer. Money behaves the same way — the goal has to mean something to survive the boring middle.
One client of mine put this into sharp focus. She'd tried three different budgeting apps over two years, each one abandoned within a few weeks despite genuinely wanting to save more. When we sat down and worked through what she actually valued, it turned out the number she'd been chasing, a generic six-month emergency fund recommended by a podcast, meant almost nothing to her personally. What she actually wanted was to be able to leave a job she disliked without panicking about money first. Once we reframed the exact same savings target as 'quit-any-job-you-hate money' instead of a generic emergency fund, she hit the goal in under a year, not because the math changed at all, but because the goal finally connected to something she genuinely cared about protecting.
Why Generic Financial Goals Usually Fail
Most financial advice hands you a number — save 20% of income, build a six-month emergency fund, retire with a million dollars — without connecting it to anything personal. Numbers without meaning are easy to abandon the moment life gets stressful or an unexpected expense appears, because there's no emotional anchor holding the behavior in place.
Behavioral economics research on financial decision-making consistently finds that people stick with savings and spending plans longer when they're tied to a specific, personally meaningful outcome rather than an abstract target. This is closely related to the broader psychology explored by the American Psychological Association on how identity and motivation interact with long-term behavior change, money included.
How to Identify Your Actual Financial Values
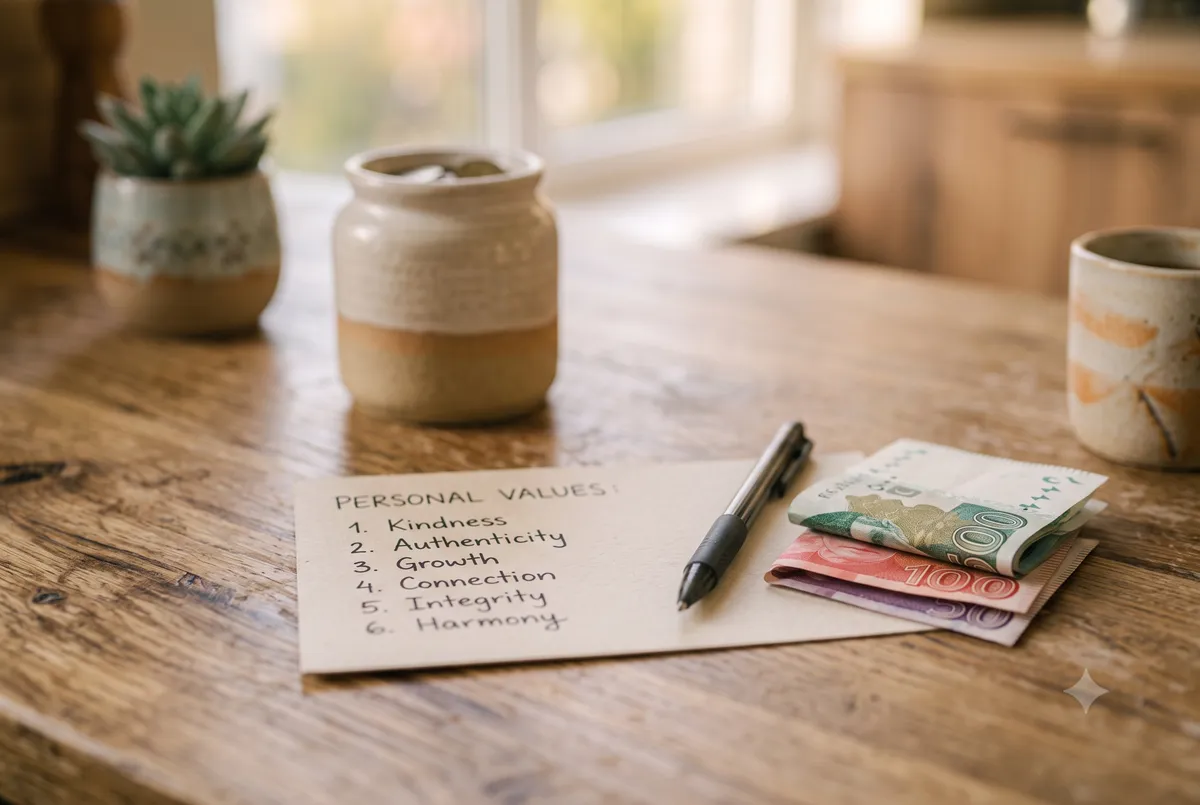
Before you can set values based financial goals, you need real clarity on what your values actually are — not what sounds impressive, but what genuinely drives your decisions. This exercise takes about 20 minutes and consistently surfaces answers people didn't expect from themselves.
- List the five purchases or experiences from the last two years that felt most worth the money, no matter the price.
- For each one, ask what underlying value it served (freedom, connection, security, health, creativity).
- Look for repeated themes across your five answers — this is your real value hierarchy, not your stated one.
- Rank your top three values in order, since most financial trade-offs come down to choosing between two things you care about.
- Write one sentence connecting each top value to a concrete money behavior (for example, 'because I value freedom, I keep fixed monthly expenses under 50% of income').
The Minimalist Wealth Framework
Minimalist wealth building isn't about deprivation — it's about spending deliberately on the few things tied to your top values and cutting ruthlessly everywhere else. In practice, this usually means a much simpler budget than most financial advice suggests: three to four spending categories instead of fifteen, with everything outside those categories treated as optional by default. This is a meaningfully different starting point than a traditional personal budget, which typically begins with expense categories rather than with the values those expenses are supposed to serve.
This is where values based financial goals actually change daily behavior. If your top value is freedom, a subscription service or upgraded car lease that increases your fixed monthly obligations works directly against that value, regardless of how affordable it looks on paper in isolation.
Setting Goals That Map to Your Values
Once you know your top values, translate each into one specific, time-bound financial goal rather than a vague intention. 'Value freedom' becomes 'save six months of essential expenses by next October.' 'Value health' becomes 'set aside $200 monthly for preventive care and movement, protected before discretionary spending.'
This translation step matters because vague values don't create action on their own — they need a concrete number and deadline attached. If sticking to new financial habits has been a recurring struggle, building them through identity-based habit strategies tends to work far better than relying on willpower or motivation alone.
- Freedom-oriented goal example: build a 6-month expense buffer within 18 months.
- Security-oriented goal example: max out an emergency fund of $10,000 before increasing any discretionary spending.
- Health-oriented goal example: allocate a fixed monthly amount to preventive care, unaffected by other budget cuts.
- Connection-oriented goal example: budget a specific annual amount for travel or gatherings with family, treated as non-negotiable.
Avoiding Comparison-Driven Money Decisions
One of the biggest threats to values based financial goals is comparison — seeing a peer's new car, house, or vacation and adjusting your spending to match, even when it has nothing to do with your own stated values. This pattern, often described as a scarcity mindset switching to a sustainable wealth mentality, is exactly the shift that protects your goals from social pressure.
A simple guardrail: before any purchase over a threshold you set (say, $150), ask which of your top three values it actually serves. If the honest answer is 'none, I just saw someone else have it,' that's useful information, not a reason for guilt.
Reviewing and Adjusting Your Goals Over Time
Values shift as life circumstances change — a new relationship, a health scare, a career pivot — and your financial goals should shift with them. Schedule a values and money review every six months, not just an annual budget review. Ask whether your top three values from last time still hold, and adjust your goals accordingly rather than sticking rigidly to a plan built around an old version of yourself.
This periodic review is also a natural time to check whether your spending has quietly drifted away from your stated values, which happens gradually and rarely announces itself. Catching the drift every six months keeps minimalist wealth building sustainable rather than something that only exists on the day you first wrote the plan.
Common Mistakes When Setting Values-Based Financial Goals
The most common mistake is choosing values that sound admirable rather than ones that actually drive your behavior. 'I value generosity' is a nice sentence, but if your last twelve months of spending show almost nothing directed toward the people or causes you claim to care about, generosity isn't actually your operating value yet, whatever you'd like to believe about yourself. The purchase-review exercise described earlier exists specifically to catch this gap between stated values and lived values, because spending data is far more honest than self-description.
A second mistake is picking too many values at once, which recreates the same overwhelm that made generic budgets fail in the first place. Three genuinely prioritized values, each with one concrete financial goal attached, consistently outperforms a longer list of five or six values that all compete for the same limited monthly income. A third mistake is treating values based financial goals as a one-time exercise rather than a living framework — writing the values down once and never revisiting them defeats the entire purpose, since values that aren't actively checked against your spending quietly stop influencing it within a few months.
- Mistake: choosing values that sound admirable instead of values your spending data actually supports.
- Mistake: trying to prioritize five or six values instead of committing to your top three.
- Mistake: writing values down once and never checking spending against them again.
- Mistake: setting a goal amount without a deadline, which removes the urgency that drives action.
Applying This Framework at Different Life Stages
Values based financial goals look different depending on where you are in life, and it's worth being explicit about that rather than applying a one-size-fits-all version of the framework. In your twenties, with fewer fixed obligations, the framework often surfaces freedom and experience as top values, translating into goals like building a flexible emergency fund or protecting money for travel rather than locking everything into long-term, illiquid commitments. In your thirties and forties, security and family connection tend to rise in priority, often shifting spending toward things like a larger emergency buffer, education funds, or protected time-off funds that let you be present for family without financial stress overriding the decision.
Later in life, the values often shift again toward legacy, health, and simplicity — spending less on accumulation and more on experiences, health-related preventive spending, and ensuring finances are simple enough for a partner or family member to manage if needed. None of these shifts require abandoning the underlying framework; they simply require re-running the values-identification exercise every few years as your actual priorities evolve, rather than assuming the values you held at 25 will still be accurate at 55.
Frequently Asked Questions
What are values based financial goals?
They are financial targets built around your genuine personal priorities, such as freedom, security, or family connection, rather than generic numbers borrowed from financial advice. The goal is tied to what you actually care about, which makes it easier to sustain over time.
How is this different from a normal budget?
A normal budget typically starts with categories and limits, while values based financial goals start with identifying what matters most to you and then build the budget backward from those priorities. The result is usually a simpler budget with fewer, more meaningful categories.
Do I need a financial advisor to set values based financial goals?
No, the initial values-identification exercise and goal-setting can be done on your own with a notebook in under an hour. A financial advisor can be helpful later for optimizing specific investment or tax strategies once your goals are clear.
How often should I revisit my financial values?
A review every six months works well for most people, since major life changes and shifting priorities can happen faster than an annual review would catch. This keeps your goals aligned with who you actually are now, not who you were a year ago.
Can minimalist wealth building work on a lower income?
Yes, minimalist wealth building is arguably more effective on a lower income because it focuses spending only on what serves your top values and eliminates everything else, which often frees up more money than income increases alone would provide.